
1. What are Capital Allowances?
A Tax Relief for Spend on Business Assets
Capital allowances provide tax relief for capital expenditure incurred on business assets. This means you can deduct part or all of the value of certain assets from your taxable profits. Whether you’re a sole trader, partnership, or limited company, knowing which assets qualify and how to claim them can make a big difference in your final tax bill.
2. Identify Qualifying Expenditures
From machinery to fixtures
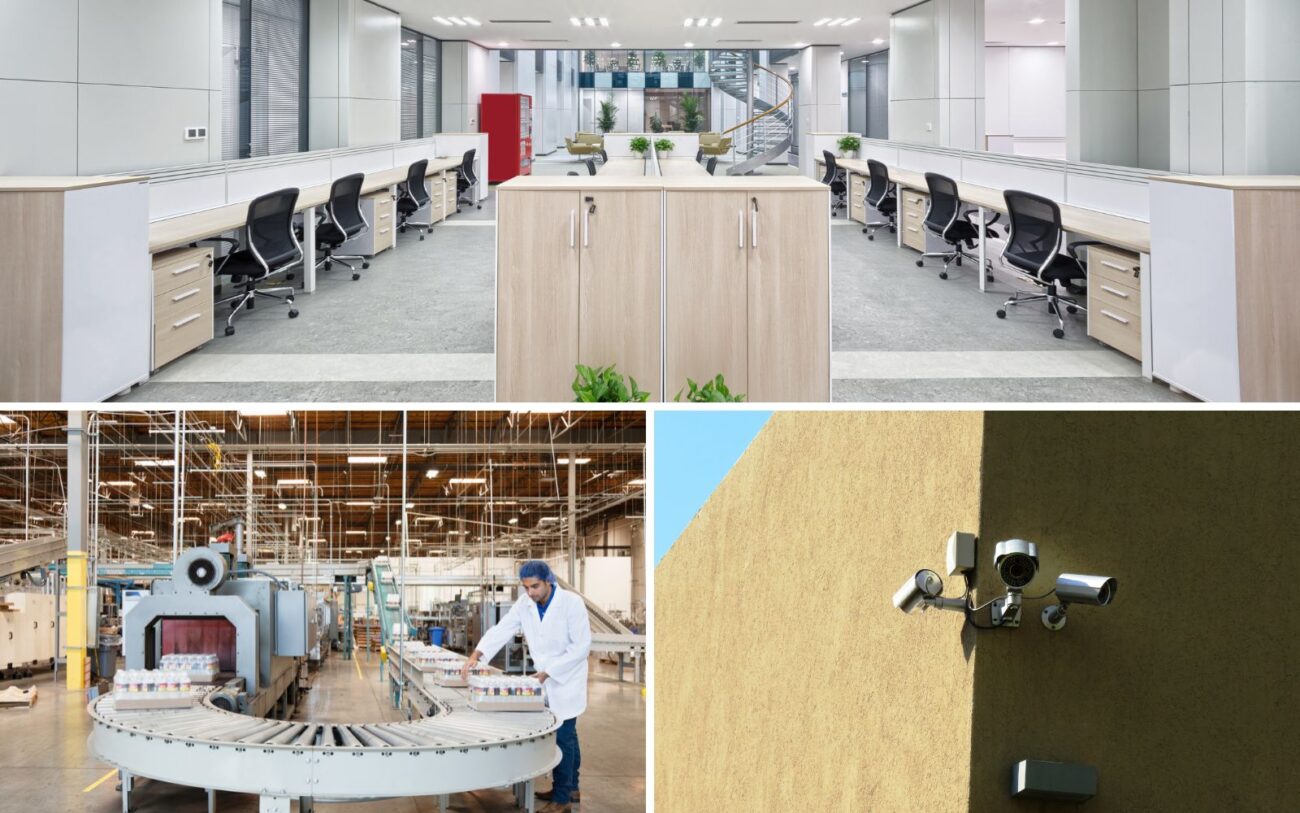
To make the most of capital allowances, start by identifying expenditures that qualify. These commonly include:
- Machinery and Equipment: Items such as office furniture, computers, and manufacturing equipment.
- Fixtures in Properties: Expenditure on fixtures such as heating, lighting, and plumbing installations could qualify under different allowances, such as the Annual Investment Allowance (AIA) or structures and buildings allowances.
3. Make the Most of the Annual Investment Allowance (AIA)
Deduct the full value
The AIA allows businesses to deduct the full value of qualifying plant and machinery costs from their profits, up to a set annual limit. For most businesses, this is the quickest and most generous way to claim capital allowances. For the tax year 2024/25, the AIA remains at a high threshold of £1 million, making it a powerful tool for those who act before the self-assessment deadline.
Tip: If you made qualifying purchases late in the 2023/24 tax year or early in the 2024/25 tax year, be sure to check how these expenditures align with your business’s financial year-end to ensure you maximise claims effectively.

4. Don’t Forget Writing Down Allowances (WDAs)
Deduct a percentage of the asset’s value
If you have investments that don’t qualify for the AIA or first-year allowances or you’re out of the window of opportunity, WDAs are a reliable option. WDAs enable you to deduct a percentage of the asset’s value each year. The rates typically range from 6% to 18% depending on the type of asset. It’s a slower route, but an essential tool for assets that exceed the AIA threshold.

5. Check Past Expenditures for Missed Claims
Potentially reveal unclaimed allowances
It’s common for business owners to overlook capital allowances on older investments. Reviewing expenditures from previous years can reveal unclaimed allowances that can be included in your current tax return. This is known as a capital allowance pool and can be claimed at the applicable WDA rates.

6. Seek Professional Guidance
Navigating capital allowance rules can be complex, especially for larger or unique investments. Consulting with a tax advisor or claims analyst can help ensure you’re not missing out on valuable tax relief. Experts can identify opportunities that are easy to overlook and guide you through accurate, timely submissions.

If you would like support from our expert team, please get in touch...
Latest News
 20 October 2026
Capital Allowances on Property Renovations: The UK Guide for Commercial Property Owners
When claiming in the year of expenditure, Capital allowances on property renovations can typically be claimed through four main routes: the Annual Investment Allowance (AIA), full expensing, first-year allowances (FYAs), and the Structures and Buildings Allowance (SBA). Which ones apply depends on what...
 25 September 2026
Unclaimed Capital Allowances in the UK: How to Recover the Tax Relief Hiding in Your Property
Unclaimed capital allowances UK-wide are far more common than most business owners realise. HMRC’s own research into capital allowances, found that businesses had limited awareness or understanding of capital allowances. This no doubt resulting in missed tax savings as they aren’t aware the...
Contact Us
Our expert team are here to help answer any of your capital allowances questions or enquires you have about your commercial property.